African sports technology is no longer a single category. It is becoming a stack.
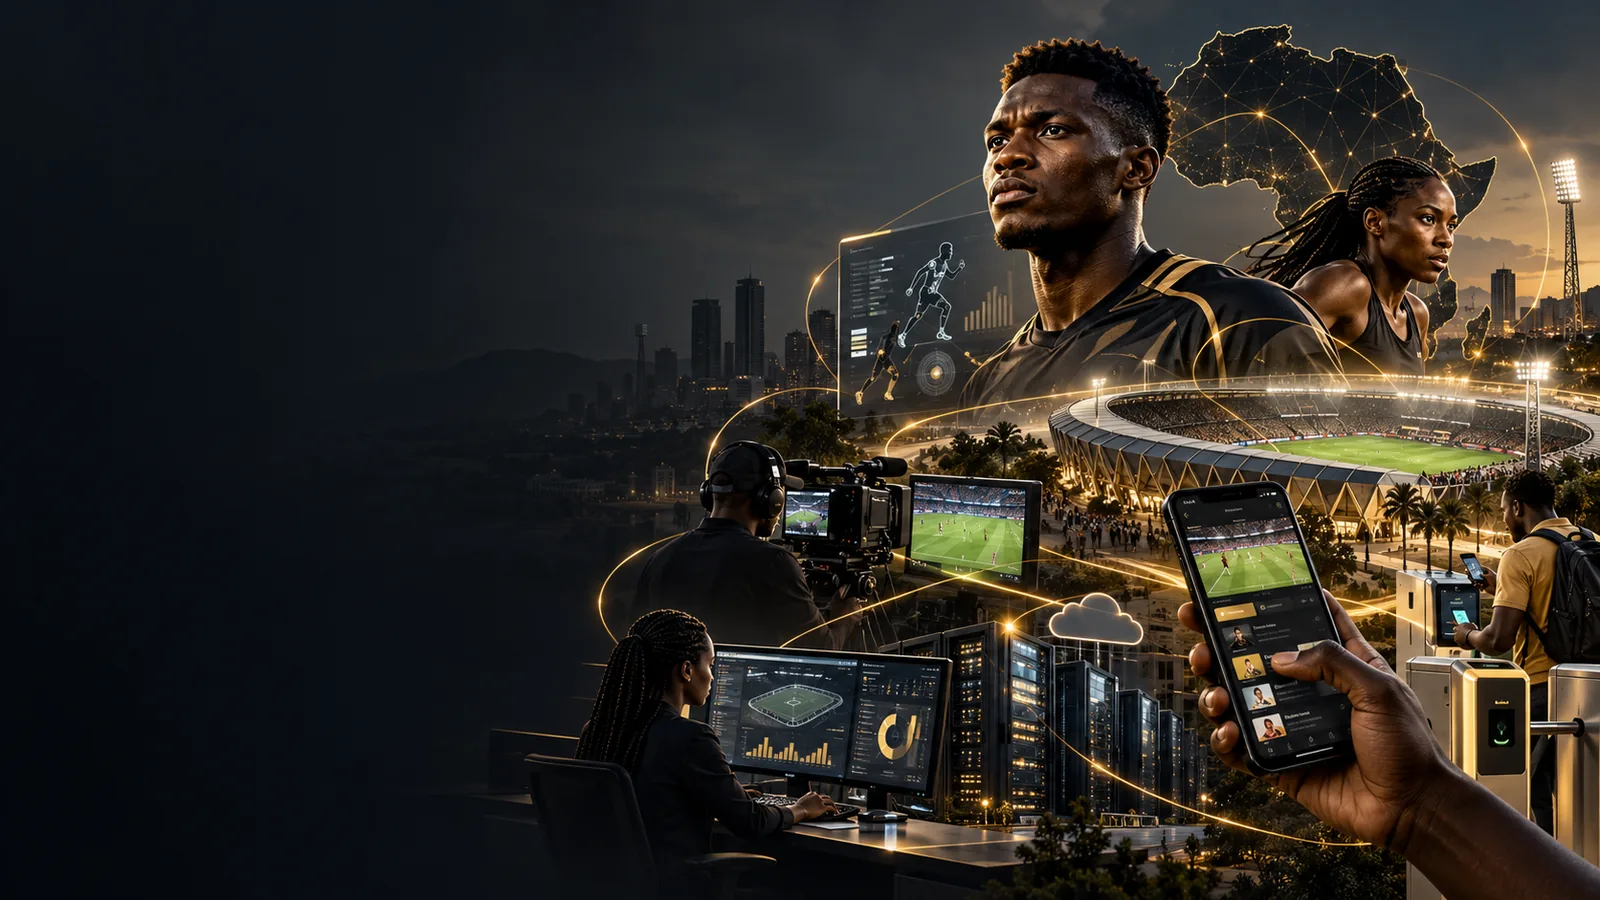
The most useful way to understand the market is therefore not by producing another list of “start-ups to watch”, but by mapping the operating problems technology is trying to solve. Across the continent, companies are forming around seven layers: talent and performance, competition operations, data and intelligence, fan engagement, ticketing and payments, media production and distribution, and venue infrastructure.
The ecosystem is early and uneven, but it is beginning to show depth.
1. Talent, scouting and performance
This layer addresses one of African sport's most persistent inefficiencies: the gap between the volume of talent and the infrastructure available to identify, verify and develop it.
Soccerlytica, based in Accra, is building AI-assisted scouting intelligence from football video. Trackus in Nigeria analyses youth-match footage to create player and team metrics. Afritech Sports, operating from Nairobi, works across wearables, performance tracking, training technology and analytics.
Global platforms such as Hudl, Veo and other automated-video providers are also increasingly relevant as African academies and clubs digitise match footage. The opportunity is not simply selling hardware; it is creating a trusted performance record that follows the athlete.
2. Competition operations and sports administration
Many leagues, federations and grassroots competitions still coordinate fixtures, registration and results through spreadsheets, messaging apps and manual processes.
Jasiri positions itself as an operating system connecting athletes, clubs, facilities, leagues and scouts. Bwoe Sports is developing connected competition infrastructure for Francophone Africa. Tisini combines live match information with tournament-management tools and ticketing.
This category has an important characteristic: once a platform becomes embedded in competition operations, it can become the source of truth for downstream data, content and commerce.
3. Data and intelligence
Africa's sports-data market remains underbuilt, particularly below the top professional competitions. That gap is creating room for locally designed intelligence products.
Tisini's live data, Soccerlytica's player intelligence and newer federation and club analytics tools are examples of a broader move toward structured datasets. The long-term commercial value is likely to come from APIs, benchmarking, scouting products, sponsorship measurement and rights intelligence rather than consumer statistics alone.
4. Fan engagement and first-party data
A fast-growing category is technology that helps rights-holders own the relationship with supporters.
FanXPlay is building participation, loyalty, fan CRM and sponsor-activation tools designed around African payment ecosystems. ProTouch in South Africa combines fan-engagement infrastructure, data and athlete-economy products. Pulego Technologies has worked on Cricket South Africa's website, app and analytics ecosystem.
This layer matters because social followers are not the same as known customers. Clubs and federations need consented first-party identities if they want to personalise content, sell directly or prove sponsorship outcomes.
5. Ticketing, commerce and payments
Africa's event-technology sector is broader than sport, but many of its capabilities are directly applicable.
Nigeria's Tix has become a major ticketing and event-management platform. Nairabox, acquired by Wakanow in 2025, illustrates the strategic value attached to distribution, transactions and lifestyle audiences. API-first ticketing models are increasingly important because they allow a sports property to keep the fan inside its own digital environment.
The next step is deeper integration with mobile money, CRM, access control and loyalty.
6. Media production and distribution
Automated cameras, cloud production, clipping, localisation and OTT infrastructure are making the long tail of African sport more producible.
This layer includes global technology providers as well as African distributors, production companies and emerging direct-to-fan platforms. The commercial opportunity is substantial because media production is a prerequisite for almost everything else: rights sales, scouting, social content, sponsor exposure and archive value.
7. Venue and connectivity technology
Smart ticketing, 5G, Wi-Fi, distributed antenna systems, digital signage, security, cashless payments and venue analytics are turning facilities into technology platforms. Projects at DP World Wanderers Stadium in Johannesburg and AFCON venues in Côte d'Ivoire demonstrate that African stadium connectivity is moving beyond basic public Wi-Fi.
A market still waiting for integration
The ecosystem has companies in almost every layer, but few rights-holders yet operate an integrated stack. That is the next opportunity.
The winning platforms will not necessarily be those with the most features. They will be the ones able to integrate into the systems around them, prove return on investment and survive the procurement realities of African sport.
SIA takeaway
African sports tech is moving from experimentation to infrastructure. The next phase will be defined by interoperability, enterprise contracts and measurable commercial outcomes. SIA's view is that the most defensible businesses will sit where data is continuously created: competition operations, performance, transactions, fan identity and media production.
Editorial source notes
- African Sports Technology Network, 2026.
- Soccerlytica; FanXPlay; Jasiri Sport; Bwoe Sports; Tisini; ProTouch; Afritech Sports; Pulego Technologies.
- TechCabal reporting on Trackus, Tix and Nairabox, 2025.
- Venue connectivity case studies from DP World Wanderers Stadium and AFCON stadium deployments.
Published by the Sports Intelligence Africa editorial team.